
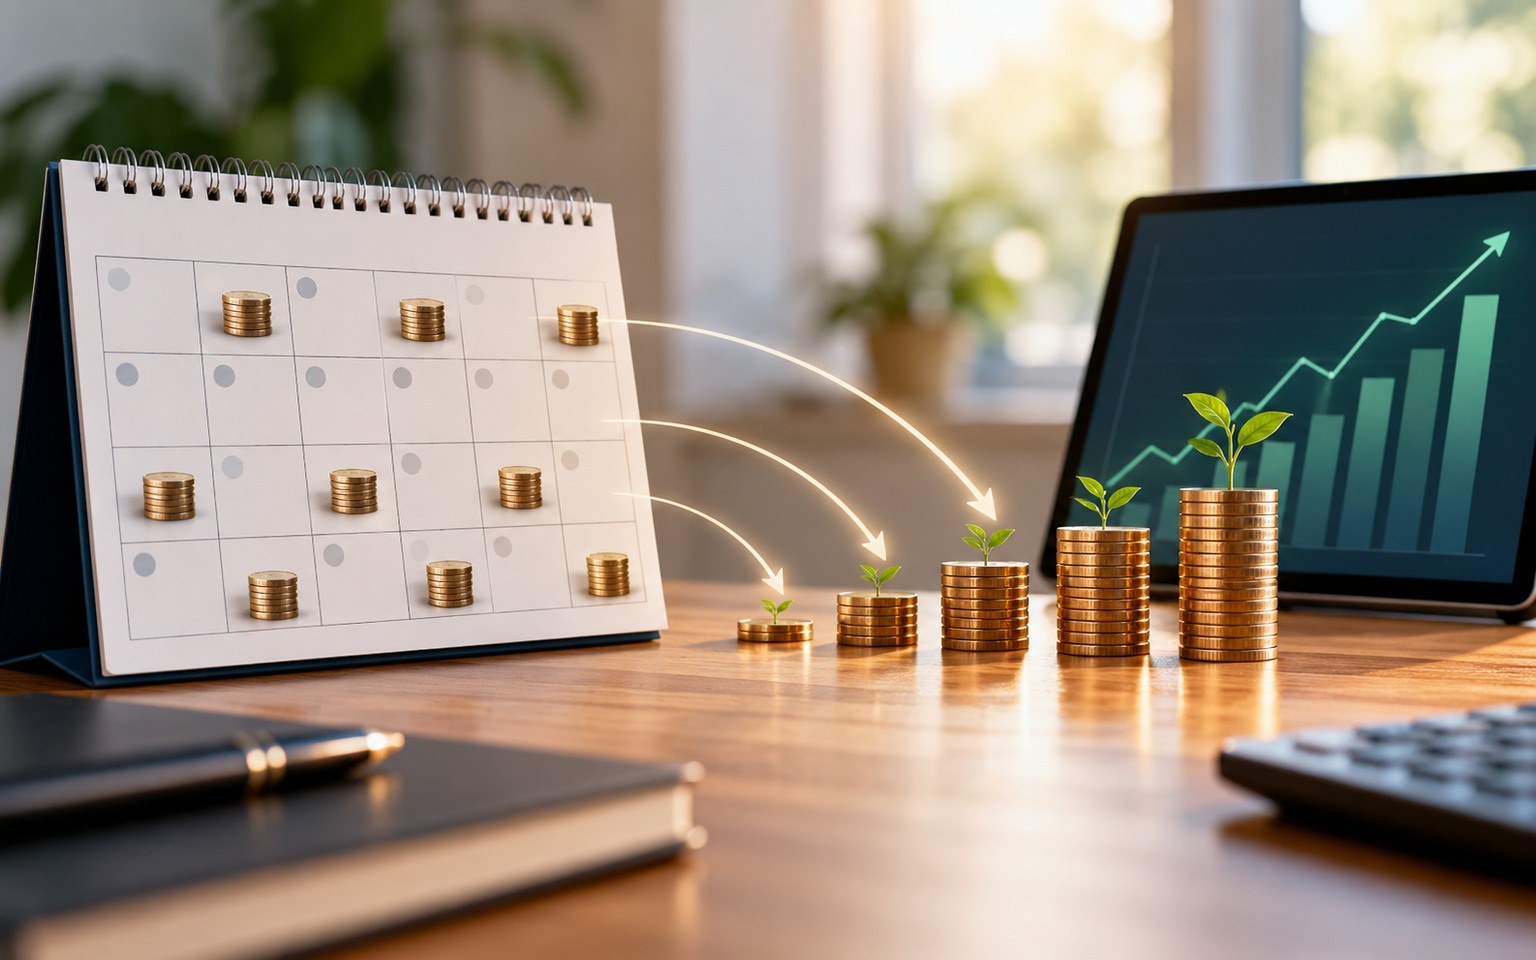
Should you invest a lump sum or contribute a smaller amount each month? Regular investing can help build a habit and reduce the need to guess the ideal day to buy. However, it does not mean the market cannot fall, that you will make a profit on your investment, or that it is suitable for everyone. It is important to understand the mechanism, the costs, and the difference between investing gradually from your salary and spreading out capital you already have available.
Regular investing means putting a set amount into an investment at recurring intervals, for example every month, regardless of the current price. When the price falls, you buy more units for the same amount; when it rises, you buy fewer. This approach can help with discipline, but it does not guarantee a return or protect against losses. The outcome is affected by the investment selected, time, fees and market developments.
How purchase-price averaging works
In English, this approach is often called dollar-cost averaging, or DCA. It is not a specific product or fund, but a way of timing purchases. Imagine investing €100 in the same investment each time. At a unit price of €10, you get ten units; at €20, you get five units.
Over two periods, you would have invested a total of €200 and acquired 15 units. Your average purchase price per unit would be approximately €13.33. This is not the arithmetic average of €10 and €20, which would be €15. The difference arises because you buy more units at the lower price for the same amount of money.
This is a simplified illustrative example that excludes fees, taxes, exchange-rate fluctuations and ongoing fund costs. The market price may subsequently fall below your average purchase price, resulting in a loss.
Regular investing from salary versus spreading out cash
The two situations may look similar, but economically they are not the same. In the first case, you invest money that you are still earning regularly. You do not have the entire future total available in advance. In the second case, you already have, for example, €6,000 and are considering whether to invest it all at once or invest €500 per month over a year.
FINRA notes that gradually investing money already available can reduce the short-term risk of investing just before a sharp decline, but it also means that part of the capital remains out of the market. If prices rise, you may miss out on some potential gains. When investing regularly from new salary income, this particular drawback of holding back cash that is already available may not arise.
It therefore makes no sense to promise that gradual investing will always deliver higher returns than a lump-sum purchase. It is not magic mathematics, but a different approach to timing and dealing with uncertainty.
Why regular investing is associated with discipline
Markets change every day, while people may feel compelled to buy only after prices have risen or, conversely, sell everything after a drop. A fixed contribution schedule can limit impulsive decisions if the investor understands it and follows it while being aware of the risks.
Automation must not replace checking what you are actually buying. Regular contributions to a narrowly focused or high-risk investment do not change its nature. If a product is not suitable for your investment horizon, buying it regularly does not automatically make it safe.
Investor.gov describes this strategy as investing equal amounts at regular intervals regardless of market fluctuations. That does not mean everyone should automatically choose it without considering their own goals and emergency savings.
Fees can change the outcome for small contributions
Consider an illustration in which you pay a fixed fee of €2 on every €50 purchase. Two euros from each payment are therefore deducted before the asset is bought—4% of the planned amount. With twelve purchases a year, transaction fees alone would total €24. This is not the fee schedule of any specific broker.
In addition to a trading fee, there may be fund expenses, currency conversion costs, a spread, a management fee or an inactivity fee. The SEC warns that even seemingly low ongoing fees reduce a portfolio's value over the long term. Therefore, compare the actual costs of the product and service, not just advertisements promising “investing from one euro”.
Check the current terms with the bank or insurance company and the investment platform, as well as its current fee schedule, key information document and tax conditions.
Can regular buying protect you from a major market decline?
No. If the investment being purchased loses value over the long term or its issuer runs into difficulties, regular buying may only increase the total amount exposed to risk. Price averaging does not erase a fall in the market value of units already purchased.
Diversification, product selection, access to liquidity and, above all, when you will need the money make a difference. If you know you will need to pay for car repairs or rent in a few months, exposing that amount to high market risk may be inappropriate, regardless of how regularly you make purchases.
Also consider keeping an emergency fund for unexpected expenses and addressing expensive debt. Without one, financial need may force you to sell an investment at exactly the time its value has fallen.
When to adjust regular contributions and what to check
From time to time, compare your portfolio's actual composition with your original goal, current fees, investment horizon and any changes in income. If the time to use the money is approaching, it may be appropriate to assess risk and liquidity rather than simply extending an automatic purchase plan without thinking.
Regular investing is therefore a way to organize contributions, not a promise of an outcome. You need to understand both the product and why you are investing the money. Every return example is only a model, and past performance is not a guarantee of future results.
This text is for informational purposes only and does not constitute financial advice.
Sources
- Investor.gov – Dollar Cost Averaging – https://www.investor.gov/introduction-investing/investing-basics/glossary/dollar-cost-averaging
- FINRA – The Pros and Cons of Dollar-Cost Averaging – https://www.finra.org/investors/insights/dollar-cost-averaging
- Investor.gov – How Fees and Expenses Affect Your Investment Portfolio – https://www.investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins/updated
Gabriel Čatár
I'm interested in everyday things we encounter but don't always understand. From technology and personal finance to practical guides and fascinating facts about the world. At Offpitch, I focus on topics worth exploring in greater depth, checking the facts and explaining them in a clear, accessible way. My goal is to make sure readers take away something useful from every article.


